
Transfer Pricing developments – October 2026
The Cyprus Tax Department has announced significant developments in the area of Transfer Pricing (TP), introducing revised safe harbour rates for certain intra-group financing arrangements, together with a new reporting requirement for controlled financial transactions.
The changes were introduced through Circular 5/2026, issued on 12 October 2026, and the publication of a new Financial Transaction Table (FTT) template. The revised measures apply from the 2026 tax year onwards and are particularly relevant to Cyprus companies engaging in controlled financing transactions with related parties.
- Financial Transaction Table (FTT)
Purpose:
The Financial Transaction Table (FTT) aims to standardise the disclosure of specific information relating to controlled financial transactions included in the Cyprus Local File, through a prescribed reporting format, starting from the 2026 tax year.
Who is affected?
The requirement applies to persons falling within the provisions of Article 33(7) of the Income Tax Law (Law 118(I)/2002), whose aggregate controlled transactions falling under the Financial Transactions category exceed the applicable thresholds, or would exceed such thresholds if calculated on an arm’s length basis.
Transactions covered:
The reporting requirement covers the following categories of financial transactions:
- Provision of financing: Loans receivable, trade receivables of a financing nature and other receivables of a financing nature.
- Receipt of financing: Loans payable, trade payables of a financing nature and other payables of a financing nature.
Submission method and deadline:
The Financial Transaction Table must be submitted electronically through the Tax For All (TFA) System, as an attachment to the Summary Information Table (SIT) of Controlled Transactions.
The submission deadline will coincide with the applicable deadline for filing the company’s Income Tax Return.
- Revised Simplification Measure Rates:
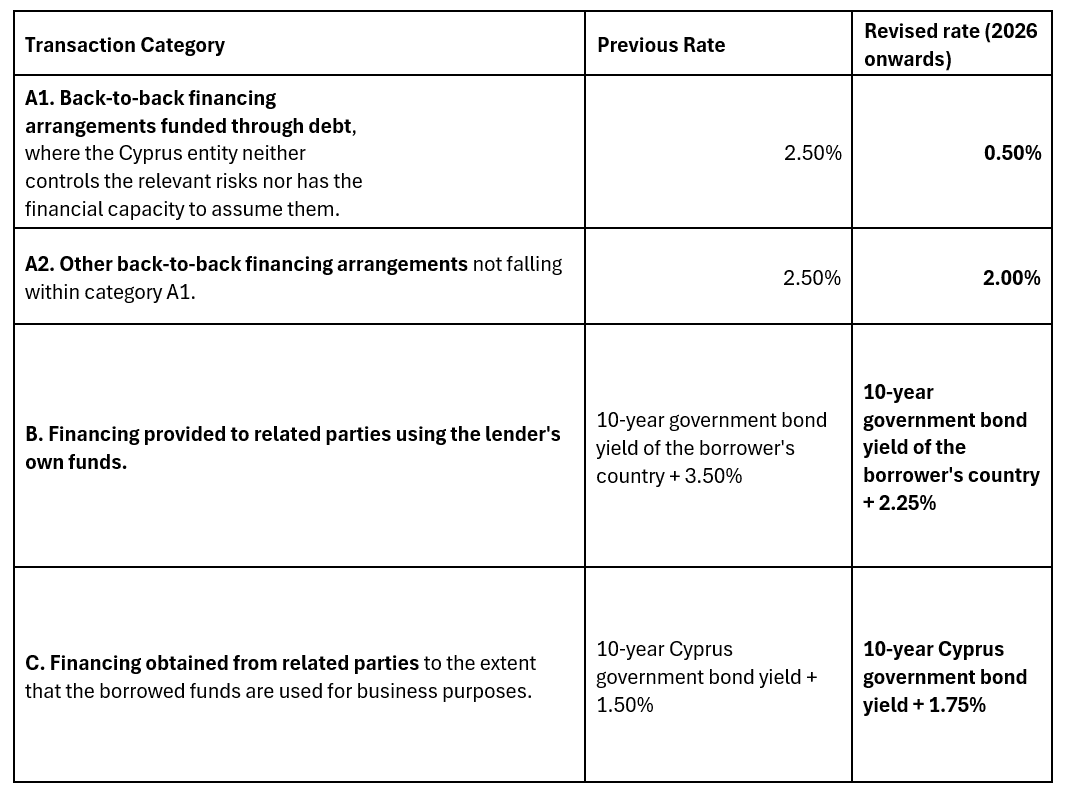
Circular 5/2026 introduces amendments to the simplified Transfer Pricing measures previously established under Circular 6/2023, revising the safe harbour rates applicable to certain intra-group financing arrangements.
The revised rates apply from the 2026 tax year onwards and concern qualifying transactions undertaken by taxpayers who are exempt from the obligation to prepare a Cyprus Local File.
The revised rates are summarised below:
Important considerations when applying the revised rates:
- The above rates represent amounts before the deduction of any applicable taxes.
- For categories B and C, the relevant 10-year government bond yield is determined by reference to the rate published as at 31 December of the preceding calendar year.
- Where a financing arrangement under categories B or C is denominated in a currency other than the borrower’s domestic currency, the applicable benchmark should be the 10-year government bond yield of the borrower’s country, denominated in the currency of the loan, provided that the relevant rate is published on the Cyprus Tax Department’s website.
- Where no such reference rate is available, taxpayers should contact the Tax Department’s Intra-Group Transactions Unit for guidance on the appropriate rate.
What remains unchanged?
The simplified 5% mark-up on relevant expenses for qualifying low value-adding intra-group services remains unchanged. All other conditions and provisions of Circular 6/2023 relating to the application of the simplified Transfer Pricing measures continue to apply.
Conclusion
The changes introduced through Circular 5/2026 represent an important update to the Cyprus Transfer Pricing framework, both in terms of the reporting obligations for controlled financial transactions and the revised safe harbour rates applicable to intra-group financing arrangements.
Cyprus companies engaging in controlled financial transactions with related parties should review their existing arrangements to assess the impact of the revised measures, ensure compliance with the new reporting requirements and determine whether any adjustments to their Transfer Pricing documentation are necessary.